
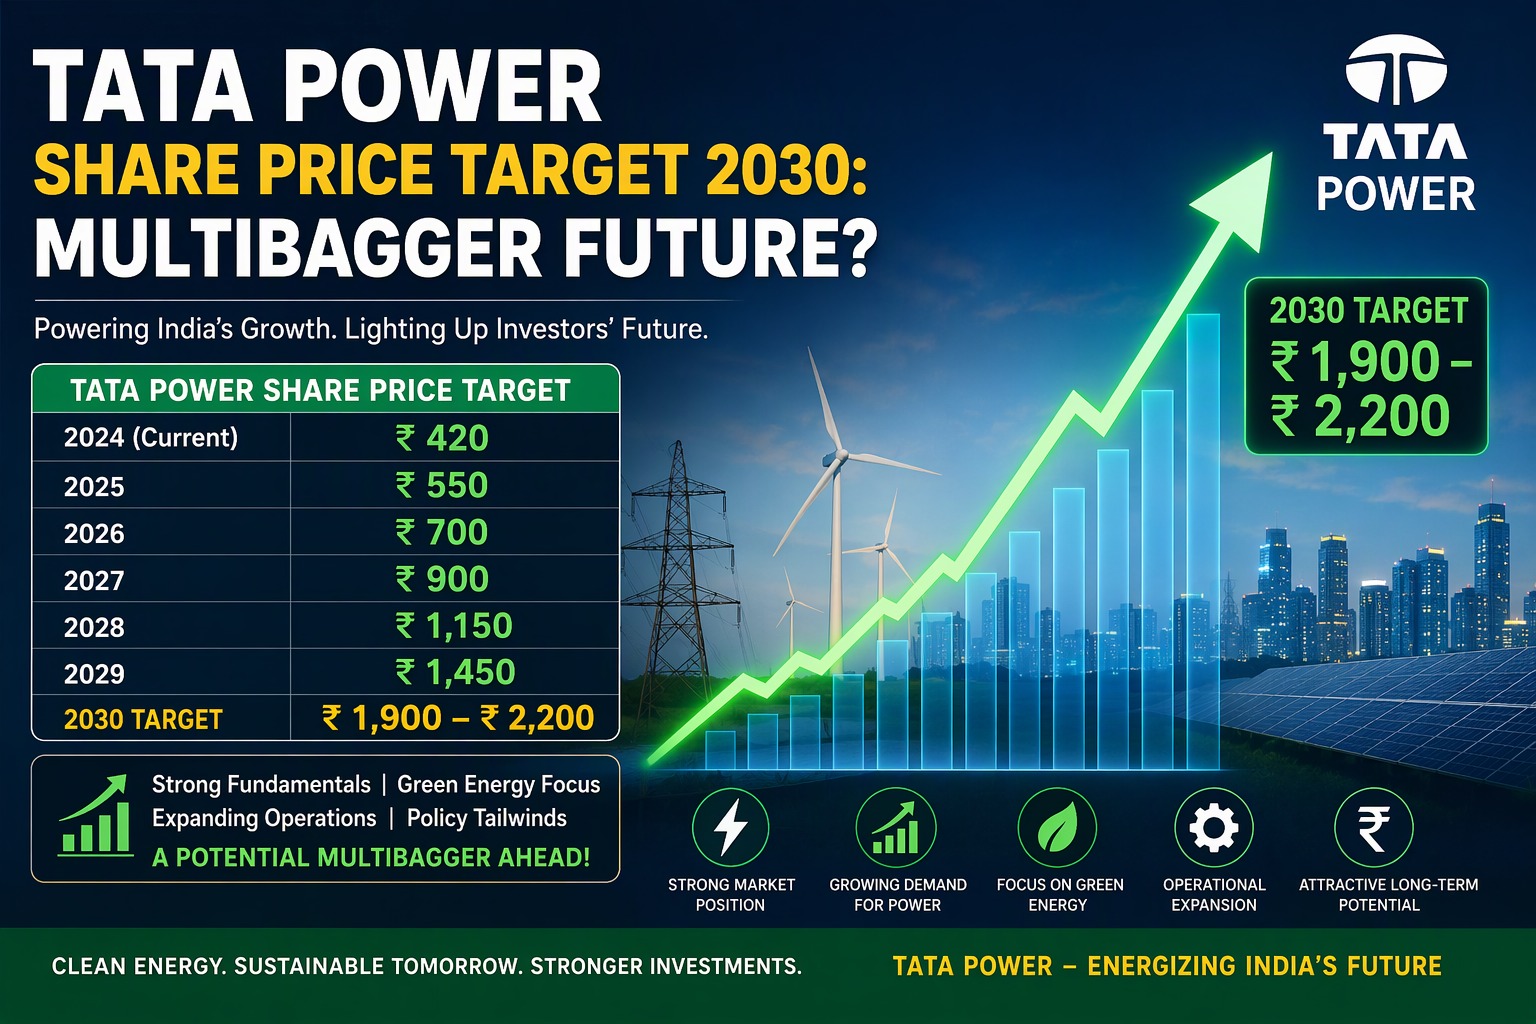
What will Tata Power’s share price look like in 2030? This is the question every serious long-term investor is asking as India accelerates its renewable energy transition and power demand surges to unprecedented levels. Based on current growth trajectories, analyst projections, and the company’s aggressive expansion plans, Tata Power could deliver multibagger returns by the end of this decade—but only if certain critical factors align in its favor.
In this comprehensive analysis, we dissect every major catalyst, risk, and financial metric that will shape the Tata Power share price in 2030. Whether you’re a retail investor building your retirement portfolio or a trader evaluating long-term positions, this deep dive will give you the clarity you need.
Key Takeaways
- Tata Power is positioned as India’s largest integrated power company with a 13 GW+ generation capacity target by 2027.
- Analyst consensus suggests a potential share price range of ₹600–₹900 by 2030, driven by renewable energy expansion.
- The company’s 4 GW solar module manufacturing facility and EV charging network are key long-term growth catalysts.
- Regulatory risks, debt levels, and execution challenges remain the primary threats to bullish projections.
- Long-term investors should accumulate during market corrections rather than chasing short-term rallies.
Why Tata Power Commands Attention in India’s Energy Landscape
Tata Power Company Limited, a part of the illustrious Tata Group, has evolved from a traditional thermal power generator into a diversified energy giant. As a result, the company now operates across generation, transmission, distribution, and renewable energy—making it a uniquely positioned play on India’s entire power value chain.
Furthermore, the Indian government’s commitment to achieving 500 GW of non-fossil fuel capacity by 2030 creates an enormous tailwind for companies like Tata Power. As a result, investors who recognize this structural opportunity early stand to benefit significantly.
Current Market Position and Financial Snapshot
As of 2025, Tata Power’s market capitalization hovers around ₹50,000–₹55,000 crore, with the stock trading in the ₹370–₹420 range. The company reported consolidated revenue of about ₹5,000 crore in FY24, with net profit exceeding ₹4,000 crore. Moreover, its EBITDA margin has consistently improved, reflecting operational efficiency gains.
However, the 2030 outlook hinges on the company’s capital expenditure roadmap. Tata Power has committed to investing over ₹70,000 crore in renewable energy projects over the next five years. This massive reinvestment strategy is designed to dramatically transform the company’s revenue mix.
Tata Power Share Price in 2030: The Growth Catalysts That Matter
Several powerful catalysts will drive the Tata Power stock forecast over the next five to six years. Understanding these factors is essential for any investor evaluating the stock’s long-term potential.
1. Renewable Energy Capacity Expansion
Tata Power aims to achieve 25 GW of renewable energy capacity by 2027, up from approximately 7.5 GW currently. Additionally, the company plans to add another 5–7 GW by 2030. Therefore, by the end of the decade, renewables could constitute over 60% of its total generation portfolio.
This shift is not merely about capacity addition. It fundamentally changes the revenue quality — renewable energy contracts offer long-term, inflation-linked power purchase agreements (PPAs) that provide predictable cash flows for 25 years or more.
2. Solar Module Manufacturing and the PLI Scheme
The company’s 4 GW integrated solar manufacturing facility in Tamil Nadu is a game-changer. Because of the Production Linked Incentive (PLI) scheme, Tata Power receives financial benefits for every unit of solar module manufactured domestically. This vertical integration reduces dependence on Chinese imports and significantly improves margins.
As a result, the solar manufacturing business alone could contribute ₹8,000–₹10,000 crore in annual revenue by 2030, according to industry estimates.
3. EV Charging Infrastructure Leadership
Tata Power currently operates over 50,000 EV charging points across India — the largest network in the country. Moreover, with India’s EV market projected to grow at a CAGR of 49% through 2030, this business segment could become a significant revenue contributor.
The company plans to expand to 2,00,000 charging points by 2030. Consequently, this infrastructure moat creates a recurring revenue stream that competitors find difficult to replicate.
4. Transmission and Distribution Modernization
Tata Power’s transmission and distribution (T&D) business serves over 12 million consumers across multiple states. The company is also investing heavily in smart grid technology, which reduces aggregate technical and commercial (AT&C) losses and improves profitability.
The T&D segment generates stable, regulated returns — providing a defensive cushion during market downturns. This stability is precisely what long-term investors seek when projecting returns over a 5–6 year horizon.
5. India’s Insatiable Power Demand
India’s peak power demand has already crossed 250 GW in 2025, and projections suggest it could reach 400+ GW by 2030. As a result, every major power company in India stands to benefit from this structural demand-supply gap.
As the largest integrated player, Tata Power is uniquely positioned to capture a disproportionate share of this growth. Therefore, the macro tailwind alone provides a strong foundation for the stock’s appreciation.
Financial Projections: Where Could the Stock Be by 2030?
Predicting an exact share price for 2030 involves considerable uncertainty. Nevertheless, we can construct reasonable scenarios based on earnings growth, sector multiples, and macroeconomic assumptions.
Bull Case Scenario: ₹800–₹1,000
In this scenario, Tata Power successfully executes its renewable expansion plan, achieves 30+ GW of total capacity, and reports a net profit of ₹12,000–₹15,000 crore by FY2030. Consequently, at a reasonable P/E multiple of 25–30x (justified by the renewable energy premium), the stock could trade between ₹800 and ₹1,000.
Base Case Scenario: ₹600–₹750
Under normal execution conditions, the company achieves 20–22 GW of capacity with a net profit of ₹8,000–₹10,000 crore. At a P/E of 22–25x, this translates to a share price of ₹600–₹750 by 2030.
Bear Case Scenario: ₹350–₹450
If execution delays, regulatory hurdles, or a prolonged high-interest-rate environment persist, the stock could remain range-bound. In this scenario, earnings grow modestly to ₹5,000–₹6,000 crore, and the stock trades at a P/E of 18–20x — implying limited upside from current levels.
Risks That Could Derail the 2030 Target
Investors must approach this stock with clear eyes. Despite the attractive growth narrative, several risks could materially impact the share price trajectory.
- High Debt Levels: Tata Power’s debt-to-equity ratio remains elevated due to massive capex commitments. Therefore, rising interest rates could squeeze margins and delay profitability improvements.
- Regulatory Uncertainty: Changes in tariff policies, renewable purchase obligations, or PLI scheme modifications could disrupt revenue projections.
- Execution Risk: Adding 15+ GW of renewable capacity in five years is an enormous operational challenge. Any delays directly impact revenue timelines.
- Competition: Adani Green, NTPC, and ReNew Power are aggressively expanding their renewable portfolios, intensifying competition for project bids.
- Land Acquisition Challenges: Large-scale solar and wind projects require significant land, which can lead to delays and cost overruns in India.
Expert Opinions and Analyst Sentiment
Leading brokerages have maintained a bullish stance on Tata Power’s long-term prospects. Motilal Oswal, for instance, has projected a target price of ₹550–₹600 for the near term, with a “Buy” rating. Similarly, ICICI Direct and HDFC Securities have highlighted the company’s renewable energy pipeline as a key value driver.
Moreover, foreign institutional investors (FIIs) have steadily increased their holdings in Tata Power over the past two years. This sustained institutional interest reflects global confidence in India’s energy transition story — and Tata Power’s central role within it.
However, some analysts caution that the stock’s current valuation already prices in significant growth. As a result, investors should focus on accumulating during corrections rather than chasing momentum.
Investment Strategy: How to Approach Tata Power for 2030
Given the long investment horizon, a disciplined strategy is paramount. Here are actionable recommendations for investors targeting the 2030 timeframe.
Dollar-Cost Averaging (SIP Approach)
Rather than investing a lump sum, consider spreading your investment across 12–24 months through a systematic investment plan. This averages your purchase price and significantly reduces timing risk.
Accumulate During Corrections
Historically, Tata Power has corrected 20–30% during broader market downturns. Therefore, these pullbacks present ideal accumulation opportunities for long-term holders.
Monitor Quarterly Execution
Track the company’s quarterly disclosures for renewable capacity additions, debt reduction progress, and order book growth. These metrics are leading indicators of future earnings potential.
Portfolio Allocation
Given the inherent risks, avoid allocating more than 5–8% of your total equity portfolio to a single stock. In addition, balance your exposure with other quality names in the infrastructure and banking sectors.
The Bottom Line: Is Tata Power a Multibagger Candidate for 2030?
The evidence overwhelmingly suggests that Tata Power is structurally positioned to benefit from India’s energy transition. Furthermore, the company’s integrated business model, ambitious renewable targets, and Tata Group backing create a compelling long-term investment thesis.
However, the path to 2030 will not be linear. Consequently, investors must stay patient, disciplined, and long-term. Those who stay the course through interim volatility are most likely to capture the full upside potential of this remarkable story.
In conclusion, while no one can predict the exact Tata Power share price in 2030, the convergence of macro tailwinds, sectoral growth, and company-specific execution makes a strong case for substantial wealth creation over the next five to six years.
Frequently Asked Questions
What is the projected Tata Power share price by 2030?
Based on analyst projections and growth modeling, Tata Power’s share price could range between ₹600 and ₹900 by 2030 under base-to-bull scenarios. This projection assumes successful execution of renewable energy expansion plans, steady earnings growth of 15–20% annually, and a reasonable P/E multiple of 22–28x. However, actual outcomes depend on market conditions, regulatory changes, and execution efficiency.
Is Tata Power a good long-term investment for 2030?
Tata Power represents a compelling long-term investment opportunity because of its leadership in India’s renewable energy transition, diversified business model, and strong backing from the Tata Group. The company’s aggressive capex in solar manufacturing, EV charging infrastructure, and renewable generation positions it favorably for the next decade. Nevertheless, investors should be aware of debt-related risks and execution challenges before committing capital.
What factors will drive Tata Power’s stock price growth by 2030?
The primary growth drivers include: (1) renewable energy capacity expansion to 25–30 GW, (2) solar module manufacturing revenues boosted by the PLI scheme, (3) EV charging network growth to 2,00,000 points, (4) stable regulated returns from transmission and distribution, and (5) India’s surging power demand expected to reach 400+ GW peak by 2030. Additionally, improving EBITDA margins and debt reduction will enhance valuation multiples.
What are the major risks to Tata Power’s share price target for 2030?
Key risks include elevated debt levels that could strain cash flows if interest rates remain high, regulatory policy changes affecting tariffs and renewable obligations, execution delays in large-scale project implementation, intense competition from Adani Green and NTPC, and land acquisition bottlenecks. Global supply chain disruptions for solar components could also affect project timelines and profitability.
How does Tata Power compare to other renewable energy stocks in India?
Tata Power stands out for its integrated business model spanning generation, transmission, distribution, and solar manufacturing—a combination no other Indian company matches at this scale. While Adani Green Energy focuses purely on renewables and ReNew Power operates primarily in wind and solar generation, Tata Power offers diversification across the entire power value chain. As a result, it offers a more balanced risk-reward profile than pure-play renewable competitors.